Blocked Account Sperrkonto Germany: 2026 Bank Guide
Opening a Bank Account & Blocked Account (Sperrkonto) in Germany for Indians (2026)
Blocked Account Sperrkonto Germany rules confuse most first-time applicants, mainly because two different accounts get mixed up. One proves you can afford Germany before your visa is even issued. The other is what you’ll actually use once you land. This guide separates the two clearly, with current 2026 amounts, provider options, and a realistic step-by-step timeline.
Sperrkonto vs Girokonto: What’s the Difference
A Sperrkonto (blocked account) is a locked savings account. You fund it before applying for your visa, as proof you can support yourself. Money releases in fixed monthly amounts, only after you arrive in Germany.
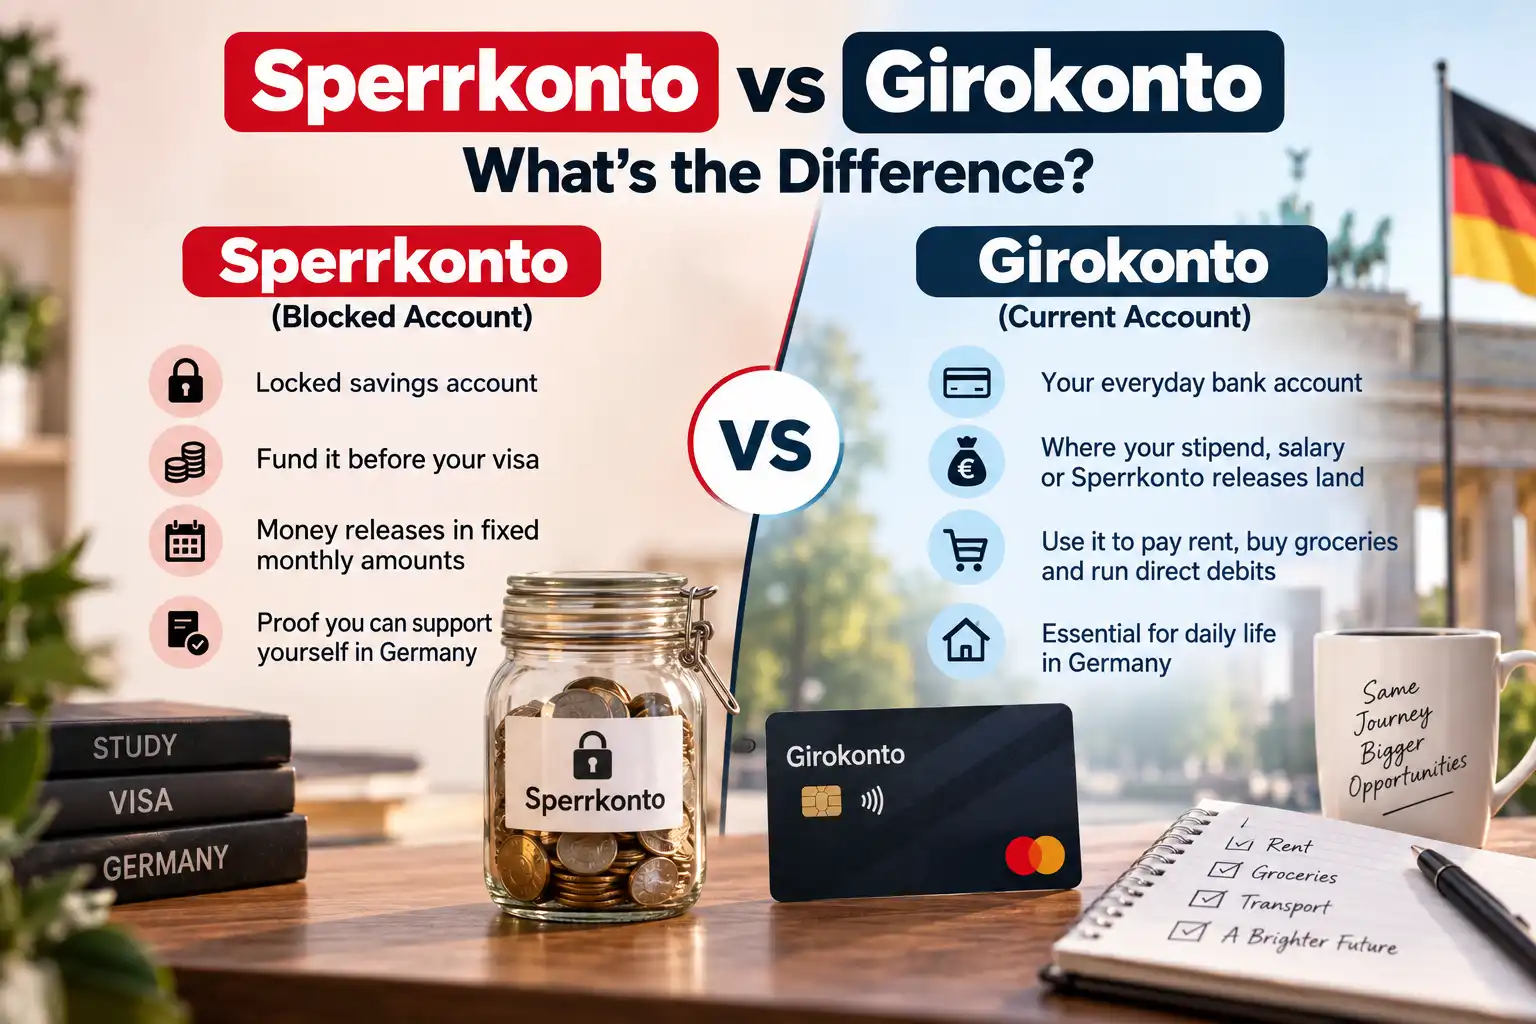
A Girokonto is your everyday current account. It’s where your stipend, salary, or Sperrkonto releases actually land. You use it to pay rent, buy groceries, and run direct debits. Most students and trainees end up needing both, not just one.
How Much You Need in Your Sperrkonto
For a 2026 student visa, the required amount is €11,904 for the year, released at €992 a month. If you’re applying under the Opportunity Card or a job-seeker visa instead, the figure rises to €13,092 a year, or €1,091 a month.
Transfer slightly more than the minimum where possible. Bank fees and exchange-rate spread can shave a little off the arriving amount, and falling short of the exact requirement can cause real delays.
Blocked Account Sperrkonto Germany: Which Provider to Choose
The market has narrowed recently. Coracle paused new applications in mid-2025 for a system upgrade, with no confirmed reopening date. That leaves two realistic options for most Indian applicants: Fintiba and Expatrio.
Expatrio tends to run cheaper overall, and often bundles a free Girokonto and confirmation within about a day. Fintiba is longer-established, offers instant confirmation with a credit-card payment, and works well if you need speed under a tight visa deadline. Exact fees shift often, so check both providers’ current pricing directly before deciding.
Step-by-Step: Opening Your Sperrkonto
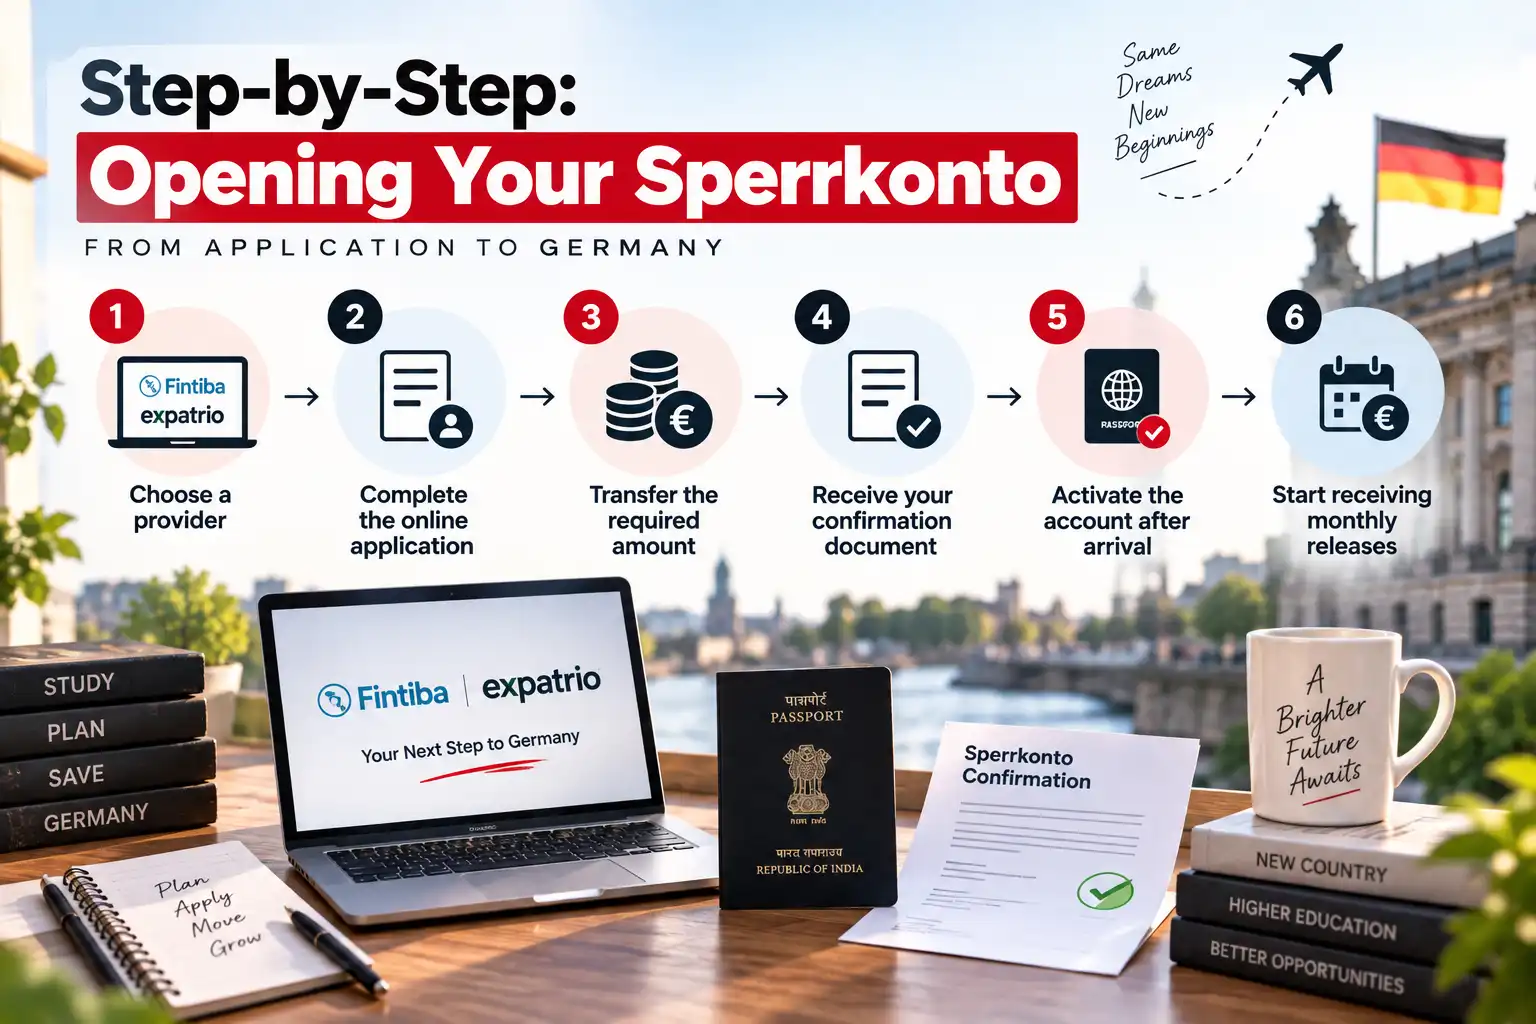
- Choose a provider — Fintiba or Expatrio, based on your budget and timeline.
- Complete the online application, using your passport for identity verification.
- Transfer the required amount, using a SEPA transfer where possible to reduce fees.
- Receive your confirmation document, which you submit with your visa application.
- Activate the account after arrival, once you have your residence permit and German address.
- Start receiving monthly releases, typically into a linked Girokonto.
Alternatives to the Sperrkonto
A Sperrkonto isn’t the only accepted proof of funds. A qualifying scholarship, such as DAAD or Erasmus+, can replace it entirely. A Verpflichtungserklärung — a formal financial obligation letter from someone already in Germany — works too, subject to embassy approval.
An education loan from an Indian bank generally supports your overall file, rather than replacing the Sperrkonto outright. Confirm the specific requirement with your embassy before assuming any alternative applies to your case.
Opening a Girokonto: Your Everyday Account
Once you’re in Germany, or even before, you’ll need a working Girokonto. Landlords want a German IBAN for rent. Language schools expect fees by bank transfer. Everyday shopping runs far more smoothly with a local debit card.
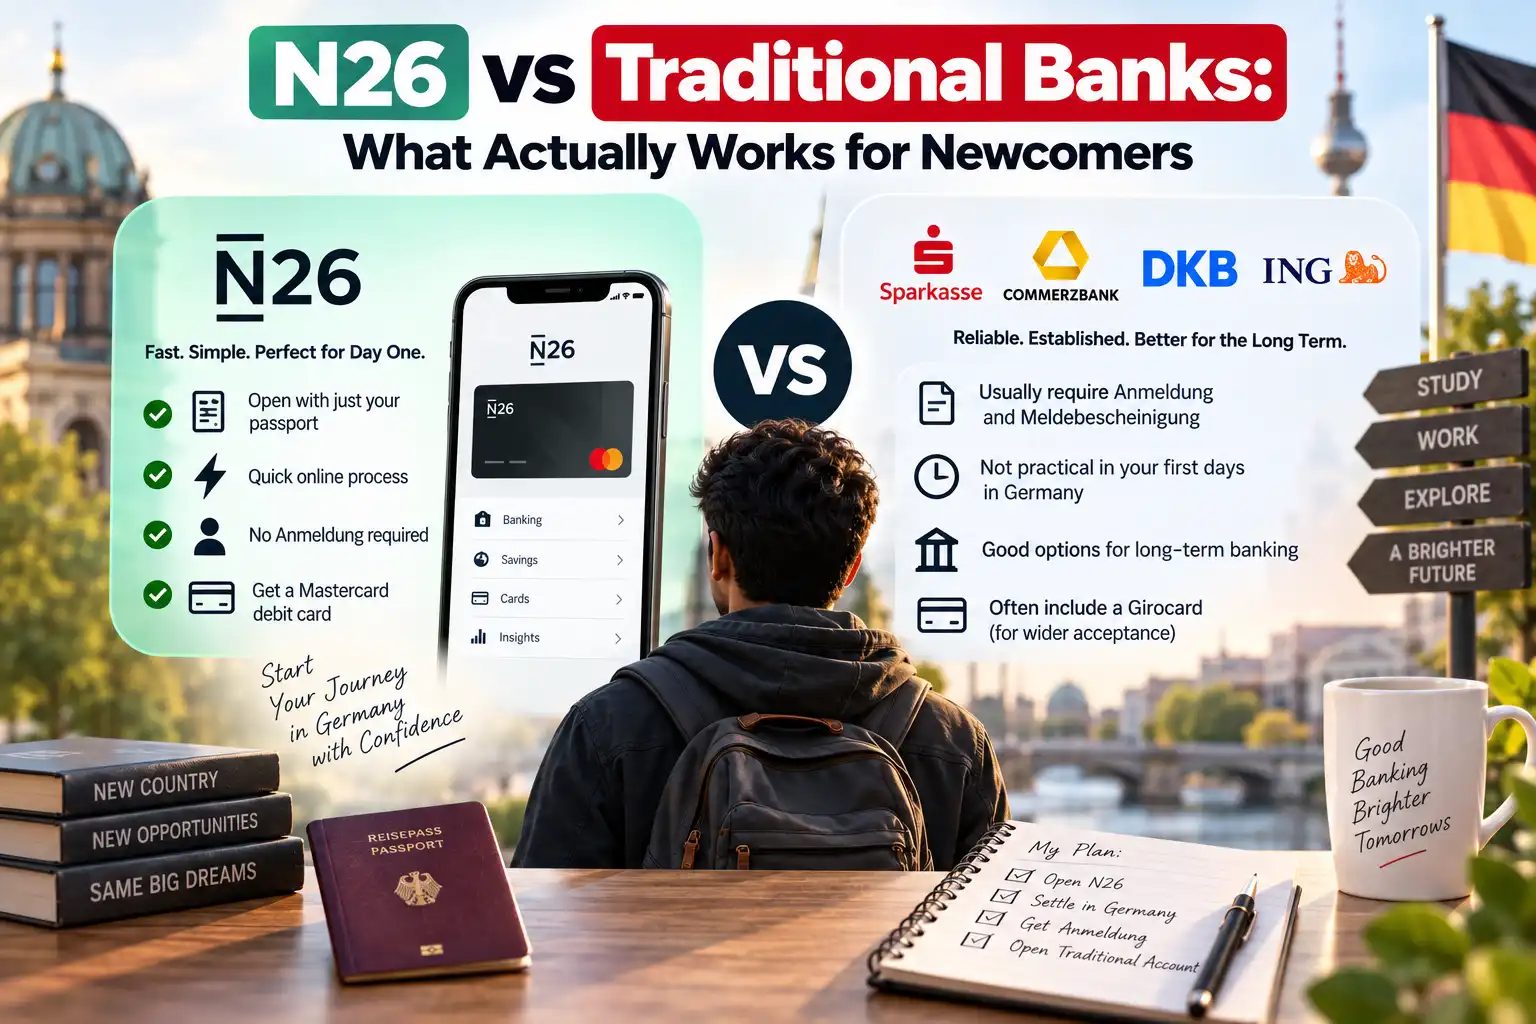
Neobanks like N26 let you open an account in minutes, using only your passport and a short video call. No German address or Anmeldung required to get started, which solves a real chicken-and-egg problem for brand-new arrivals.
N26 vs Traditional Banks: What Actually Works for Newcomers
Traditional banks — Sparkasse, Commerzbank, DKB, ING — generally require your Anmeldung and a Meldebescheinigung before they’ll open an account. That’s simply not practical in your first days in Germany. N26 sidesteps that requirement entirely, which is exactly why it’s become the default first account for most newcomers.
A common, sensible pattern: open N26 immediately for day-one banking, then add a traditional account like Commerzbank or DKB once your Anmeldung comes through.
The Girocard Problem Nobody Warns You About
Here’s a detail that catches people off guard. N26 issues a Mastercard, not Germany’s native Girocard (formerly EC-Karte). Plenty of smaller shops, bakeries, and government offices outside city centres still only accept Girocard, and post “no Visa” or “no Mastercard” signs.
This is the single most common frustration newcomers report with N26 as their only account. A second account that includes a Girocard, once you’re settled, closes that gap.
Blocked Account Sperrkonto Germany: A Realistic Timeline
Open your Sperrkonto at least six to eight weeks before your planned visa appointment. That leaves enough buffer for the transfer to clear and your confirmation document to arrive in time. Open your Girokonto either just before departure or within your first days in Germany, so you’re not stuck without a working account during a critical stretch.
Common Mistakes Indians Make
- Assuming their home bank (ICICI, SBI, or similar) can open a Sperrkonto — it can’t, since the account must sit in Germany
- Transferring the exact minimum amount, then falling short after fees and exchange-rate losses
- Waiting until arrival to think about a Girokonto, instead of opening N26 before departure
- Relying on N26 alone long-term, without realising the Girocard limitation
- Assuming an education loan alone satisfies the visa’s proof-of-funds requirement
FAQs on Blocked Account Sperrkonto Germany
How much do I need in a Sperrkonto for 2026?
€11,904 for the year for a student visa, released at €992 a month. The Opportunity Card and job-seeker visa route requires €13,092 a year instead.
Can I use my Indian bank to open a Sperrkonto?
No. The account must be held with a German-based provider. Fintiba and Expatrio are the two main options currently accepting new applications.
Do I need a Girokonto if I already have a Sperrkonto?
Yes. The Sperrkonto only holds and releases funds. You still need a regular Girokonto to actually spend that money on rent, groceries, and daily life.
Is N26 enough as my only bank account in Germany?
It works well at first, but the missing Girocard becomes a real limitation. Most newcomers eventually add a second account that includes one.
Final Thoughts
Blocked Account Sperrkonto Germany requirements aren’t as confusing once you separate the two accounts clearly in your head. Open your Sperrkonto early, with a small buffer above the minimum, and line up a Girokonto like N26 before you even land. That combination covers both your visa requirement and your first weeks of daily life in Germany.
If you’re preparing for your move, explore Germanacharya’s German courses to get comfortable handling exactly these kinds of official processes in German. Book a free 1:1 consultation to talk through your specific timeline, or browse more guides on our blog.
For official information, confirm current blocked-account amounts with the German Missions in India visa portal before opening any account, since figures update annually. For provider specifics, compare current terms directly on Fintiba’s official site and Expatrio’s site before choosing.